
Written by the USInsurance247 Content Team | Reviewed by Rubi Chauhan, Insurance Advisor, USInsurance247.com | Last updated: Ocotber 2026
Quick Answer
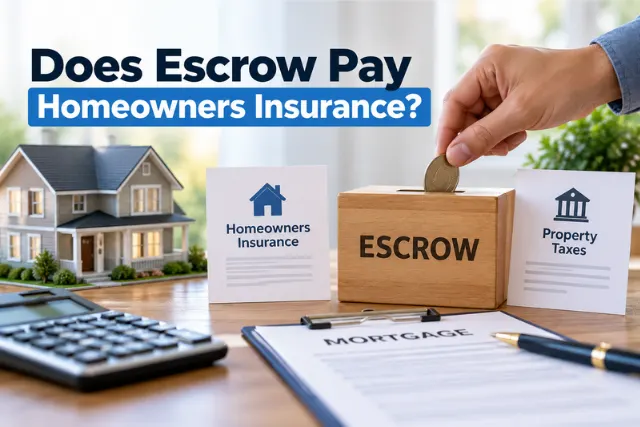
Does Escrow pay homeowners insurance? Yes, in most mortgages with an escrow account, escrow pays your homeowners insurance. Your lender collects roughly one-twelfth of your annual premium inside each monthly mortgage payment, holds it in the escrow account, and pays the insurance company directly when the premium comes due. Not every mortgage includes escrow, though — some homeowners pay their insurer directly, and with 20%+ equity you may be able to waive escrow entirely.
At a Glance
| Question | Answer |
| Does escrow pay homeowners insurance? | Usually yes |
| Does escrow pay property taxes? | Usually yes |
| Is escrow required? | Depends on the loan — FHA almost always, conventional often |
| Can you pay insurance yourself? | Yes, if your lender allows an escrow waiver |
| Does escrow pay HOA fees? | Almost never |
| Can escrow payments change? | Yes — after the annual escrow analysis |
If you just bought a home and noticed your mortgage payment is a few hundred dollars bigger than the principal-and-interest number the calculator promised, congratulations — you’ve discovered escrow. Here’s what that account actually does with your money, when it pays your insurance, and the handful of situations where the automatic system quietly fails.
What is an Escrow Account?
A mortgage escrow account (called an impound account in some western states) is a holding account your loan servicer manages to pay your property-related bills, mainly homeowners insurance and property taxes, on your behalf. For more details, read the CFPB’s guide to mortgage escrow accounts. Instead of you facing a $2,400 insurance bill and a $5,000 tax bill in lump sums, the servicer collects a slice of both inside every monthly payment and pays the bills when they’re due.
That’s why your mortgage payment has four parts, often abbreviated PITI: Principal, Interest, Taxes, and Insurance. The last two flow through escrow. (You’ll also hear “in escrow” during a home purchase — that’s a related but different use of the word, referring to a neutral third party holding funds until closing. This guide covers the mortgage escrow account you keep after closing.)
To learn more, what is an Escrow account read the article published on Escrow website.
WHERE YOUR MONTHLY PAYMENT GOES
Monthly Mortgage Payment (PITI)
↓
Split into two parts
1. Principal + Interest → Paid to the Mortgage Lender
2. Property Taxes + Homeowners Insurance → Deposited into an Escrow Account
↓
Paid by the mortgage servicer on your behalf
Lenders like escrow because your home is their collateral. Escrow helps ensure the insurance protecting that collateral actually gets paid. You benefit too: no giant lump-sum bills, no missed renewal dates, and far lower odds of an insurance lapse that could trigger expensive force-placed coverage. Learn more about why mortgage companies require homeowners insurance.
How Does Escrow Pay Homeowners Insurance? (Step by Step)
At closing, the lender estimates your annual insurance premium and property taxes, and you typically fund the escrow account with an initial deposit (often a few months’ worth).
Each month, about one-twelfth of the annual premium and taxes rides along inside your mortgage payment into escrow.
When the premium comes due — usually once a year — the servicer pays your insurance company directly. You don’t send a separate payment.
Once a year, the servicer runs an escrow analysis: it compares what it collected against what the bills actually cost, and adjusts your monthly payment up or down for the coming year.
Good to Know Escrow collects monthly but pays annually. If your insurer says “premium due” and you have escrow, the servicer handles it — but verifying the payment went out before your renewal date takes two minutes and prevents the rare-but-real servicer miss.
Which Mortgages Require Escrow?
| Loan Type | Escrow Usually Required? |
| FHA | Yes, generally for the life of the loan |
| VA | Usually yes (lender policy) |
| USDA | Usually yes |
| Conventional, less than 20% down | Usually yes |
| Conventional, 20%+ equity | Often optional, waiver may be available |
| Higher-priced mortgages | Required by federal rule for at least 5 years |
Waiving escrow: with enough equity on a conventional loan, many lenders let you drop escrow and pay insurance and taxes yourself — sometimes for a one-time waiver fee (commonly around 0.25% of the loan amount). Policies vary by lender and state, so the definitive answer lives in your mortgage agreement, not a blog post — ours included.
No Escrow? Here’s What You’re Responsible For
Without escrow, the discipline transfers to you. You’ll pay the insurer and the tax office directly, in full, on their schedules. Three habits keep you out of trouble: pay the premium before the due date, track your renewal date so a non-renewal never surprises you, and send proof of insurance to your lender whenever the policy changes, since they still require continuous coverage and still monitor it. Understand the risks of having a mortgage without homeowners insurance before deciding to go without coverage.
Escrow vs. paying the insurer yourself
| Escrow | Direct Payment |
| Automatic — near-zero effort | Full control over timing and cash |
| Smooth monthly budgeting | Annual lump-sum bills to plan for |
| Very low lapse risk | All responsibility on your calendar |
| Money sits with the servicer | Money can sit in your high-yield savings until due |
What Does Escrow Pay and Not Pay?
| Expense | Paid by Escrow? |
| Homeowners insurance | Yes |
| Property taxes | Yes |
| Flood insurance | Usually, when required — mandatory to escrow on many newer loans |
| PMI (private mortgage insurance) | Commonly |
| HOA fees | Almost never — pay your association directly |
| Utilities | No |
Common Mistake Assuming escrow covers everything property-related. HOA fees are the classic miss: homeowners assume everything is included in the mortgage payment, skip the association bill, and discover that HOAs can levy late fees and even liens. If you’re in an HOA, that bill is yours alone. Homeowners reviewing their housing expenses may also want to understand whether hazard insurance is tax deductible.
Escrow Shortages: Why Your Payment Just Went Up
Here’s the escrow experience that generates the most confused phone calls. Your insurance premium rises from $1,800 to $2,400. Escrow was collecting for $1,800 — so at the next annual escrow analysis, the account comes up short. The servicer then does two things: raises your monthly collection to match the new premium, and recovers the escrow shortage, typically spread over the next 12 payments (you can usually pay it as a lump sum instead).
That’s why a $600 premium increase can raise your monthly payment by $75 or more for a year: $50 for the new premium rate plus $25 repaying the shortfall. If you’re wondering why your mortgage payment increased, rising insurance premiums and property taxes are two factors worth checking. Servicers can also keep a cushion of up to two months of escrow charges under RESPA, which gets rebuilt after a shortage too. Your escrow balance — the amount currently sitting in the account — is on every mortgage statement, and it’s worth a glance: it should climb through the year and drop when the big bills get paid.
The happy version: if your premium or taxes drop, the analysis finds a surplus — and if it’s $50 or more, RESPA requires the servicer to refund it to you. Surpluses under $50 typically just credit against future payments.
Shopping for a cheaper policy is one way to reduce your escrow payment. Before switching, understand what hazard insurance covers and compare policy coverage and deductibles to make an informed decision.
What If Escrow Misses Your Insurance Payment?
Rare, but real: servicer errors, transfers between servicers, and insurer billing mix-ups occasionally mean a premium doesn’t arrive. Your insurer will notify you (and your lender) before canceling. If that notice lands: call the insurer and the servicer the same day, confirm the payment status, request written confirmation once it’s resolved, and keep the paper trail. Under RESPA, servicers are responsible for making escrow disbursements on time — a lapse caused by their error is their problem to fix, but only if you catch it while it’s fixable.
There’s a helpful cousin here too: an escrow advance, where the servicer fronts money the account doesn’t have to keep your insurance or taxes paid, then recovers it from you through the next analysis.
Switching Insurance Companies When You Have Escrow
Totally allowed, any time — the lender requires coverage, not loyalty. The sequence matters:
- Buy the new policy first – start date on or before the old policy’s end date.
- Notify your servicer that you’re switching.
- Send the new declarations page listing the lender as mortgagee with the correct loan number.
- Then cancel the old policy – never the other way around.
- Verify the escrow update on your next statement — right insurer, right premium.
- Watch for the old policy’s refund of unused premium — depending on who paid, it goes to you or back into escrow.
Key Takeaways
The Short Version
- Escrow usually pays your homeowners insurance – collected monthly, paid to the insurer annually.
- Not every loan has escrow – FHA nearly always does; conventional loans with 20%+ equity can often waive it.
- HOA fees are never escrow’s job – pay the association directly.
- Payment went up? Check insurance and taxes first – shortages spread over 12 months explain most increases.
- Switching insurers is fine – new policy first, declarations page to the servicer, then cancel the old one.
AI Summary
- Escrow accounts collect ~1/12 of annual homeowners insurance and property taxes in each mortgage payment and pay the bills when due.
- FHA loans generally require escrow; conventional loans with 20%+ equity may qualify for a waiver.
- Escrow typically pays homeowners insurance, property taxes, required flood insurance, and PMI — but not HOA fees or utilities.
- Annual escrow analysis adjusts payments; shortages are usually spread over 12 months, and surpluses of $50+ must be refunded under RESPA.
- When switching insurers, buy the new policy first and send the declarations page to the servicer before canceling the old one.
Conclusion
So, does escrow pay homeowners insurance? Yes, if your mortgage has an escrow account, your mortgage servicer typically collects a portion of your insurance premium with each monthly mortgage payment and pays the insurer when the bill is due. This helps you avoid large upfront payments and reduces the risk of missing your policy renewal.
However, you should still review your escrow statements, check your insurance renewal notices, and confirm that premiums are paid on time. If your mortgage does not include escrow, you are generally responsible for paying your homeowners insurance premium directly. Understanding how escrow works can help you manage your mortgage payments, avoid coverage gaps, and plan your housing expenses more confidently.
Frequently Asked Questions
Does escrow automatically pay my homeowners insurance?
Yes — the servicer collects monthly and pays the insurer directly when the annual premium is due. Your only job is verifying it happened before the renewal date.
Can I pay homeowners insurance myself instead of using escrow?
Often, once you have around 20% equity on a conventional loan — ask about an escrow waiver (a fee may apply). FHA loans generally require escrow for the life of the loan.
Why did my escrow payment increase?
Your insurance premium or property taxes rose, and the annual analysis is collecting the higher amount plus repaying the shortage over 12 months. It’s rarely your interest rate.
Does escrow pay insurance monthly?
No — it collects monthly and pays annually. Your insurer receives one full premium payment per year (or per its billing cycle), not twelve small ones.
What if my escrow account has a shortage?
You’ll get a shortage notice with two options: pay it as a lump sum or spread it over the next 12 payments. Neither is a penalty — it’s just true-up math after bills rose.
Does escrow pay flood insurance and PMI?
Usually yes for both — flood insurance is mandatory to escrow on many newer loans when required, and PMI is commonly collected through escrow. HOA fees never are.
What happens to escrow when I refinance?
The old escrow account closes and its balance is refunded to you (typically within 20–30 days of payoff), while the new loan opens a fresh account with a deposit at closing. Briefly, you fund both.
How do I know if my mortgage includes escrow?
Check your monthly statement — an escrow line item for taxes and insurance means yes. Or compare your payment to your principal-and-interest amount; if it’s noticeably higher, the difference is escrow.
Disclaimer
This article is for general informational purposes and is not financial, legal, or mortgage advice. Escrow requirements, waiver policies, cushion limits, and refund rules referenced reflect RESPA/Regulation X, CFPB guidance, and Fannie Mae/Freddie Mac servicing standards as of Ocotber 2026; specifics vary by loan type, lender, and state. Review your mortgage agreement and consult your loan servicer or a licensed professional about your situation.